Richard Hemming, Founder & Analyst
ASX: CHL
Information Technology
Technology hardware & equipment
Camplify Holdings (ASX:CHL): Is insurance the growth driver for this caravan marketplace?
“The marketplace is dominant but niche, and the group has struggled to integrate past acquisitions. The insurance business represents a very real opportunity — but this sits at the high-risk end, with a small float and exposure to travel disruption.”
Current Price
A$0.33
▲ 2.4c (+7.8%)
Our Fair Value
$0.45 – $0.55
UTRR indicative range vs current price $0.33 · high-uncertainty, small-cap coverage
Is Camplify (CHL) a buy right now?
This is an opportunity but one that sits at the high-risk end, being loss-making, a small float and the ever-present danger of travel business interruption, through bush fires or floods.
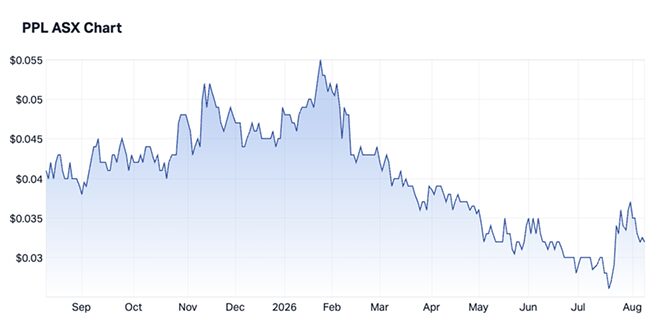
The company has a big headwind in rising fuel prices not to mention fuel security but FY26 stood out for cost control. The share price reaction has certainly been positive, with the stock climbing from 20 cents in July to over 30 cents.
Insurance is a big hurdle to RV owners listing on peer-to-peer sites like Camplify, because it often conflicts with their existing insurance. This set up puts insurance first and then Camplify provides a great opportunity to make money.
Investment Case
Bull Points
Proprietary MyWay insurance product lifts margin from ~5% (broker model) to ~28%
FY26 swung from -$10.4m to +$0.3m EBITDA on cost control
Insurance only 1% penetrated into a $1bn Australian RV insurance market
Germany launch extends MyWay beyond the core marketplace
Bear Points
Still loss-making at net profit level; small float and thin liquidity
Revenue and bookings sensitive to fuel prices and travel disruption events
Past acquisitions (PaulCamper, MyWay integration) have been difficult to digest
Limited disclosure relative to ASX 300 peers; management has not guided FY27 numbers
What’s New? Market Update.
- FY26 EBITDA turned positive at $0.3m, versus a $10.4m loss in FY25
- Second-half FY26 NPAT beat expectations by $2.1m
- Share price climbed from 20c (Jul 2026) to above 30c on the earnings turnaround
- Rising fuel prices remain a headwind to booking volumes into FY27
Who is Camplify and how does it make money?
Camplify operates a peer-to-peer marketplace connecting RV and campervan owners with hirers across Australia, New Zealand, the UK, Spain, Germany, Austria and the Netherlands. It earns a commission of roughly 30% of booking value, taking a 20% deposit at time of booking and paying owners in two instalments. Its MyWay insurance product — sold as a membership rather than a broker product — is the newer, higher-margin growth engine, and is now being extended into Germany.
Growth outlook and valuation
Camplify trades on revenue of approximately $42m against a market capitalisation below $30m — an undemanding multiple for a business moving from loss to profit. Management has flagged FY27 as an execution year, targeting stronger performance as the operating leverage in the model comes through. This remains a high-risk, small-float name: the re-rating case depends on booking volumes recovering and MyWay scaling beyond its current ~1% share of the $1bn Australian RV insurance market.
Key Risks
What could go wrong
Liquidity & float risk — small market cap and thin daily volume can amplify price moves in either direction.
Travel disruption risk — bushfires, floods or fuel price spikes directly hit booking volumes.
Integration risk — the group has previously struggled to integrate acquisitions (PaulCamper, MyWay rollout).
Disclosure risk — reporting and guidance are less detailed than larger ASX peers, making forecasting harder.
Funding risk — while net cash is currently positive ($8.6m), continued losses could require future capital raising.
“FY2027 is focused on execution. The Company expects performance to be significantly stronger than FY2026, with management concentrating on converting existing opportunities and demonstrating the operating leverage inherent in the business model.”
Bryant Henson, Chief Executive Officer
CHL share price history
This is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy, sell or hold any security.
FAQ
No. Camplify does not currently pay a dividend. The company is reinvesting cash flow into scaling its MyWay insurance product and its core RV marketplace.
Security Snapshot
Sector
Information Technology
Industry
Technology hardware & equipment
Activity
Caravan | Campervan Marketplace
ASX Code
CHL
Dividend
No Dividend
Share Price
No Dividend
Market Cap
(at A$0.33
Net Cash
$8.6M
PEER COMPARISON
KEY DATES
Independent research. This article was produced by Under The Radar Report’s editorial team and was not commissioned or paid for by Camplify Holdings Limited. See our research methodology & disclosure policy.

Richard Hemming
Founder, BA (Econ, maths statistics), FSIA
Richard is an experienced equities analyst, stockbroker, and financial editor, having worked for over 30 years in finance.