Richard is an experienced equities analyst, stockbroker, and financial editor, having worked for over 30 years in finance.
DMX Asset Management: Steven McCarthy on Count, Clover & Microcaps
Finding a small company with the potential to become a much larger business is one thing. Buying it at an attractive price and staying patient while it grows is another.
In our latest fund manager interview, Richard Hemming speaks with Steven McCarthy of DMX Asset Management about finding value at the micro-cap end of the ASX. They discuss:
- Count (CUP)
- Clover (CLV)
- LaserBond (LBL)
- Energy One (EOL)
- Kip McGrath (KME)
- Verbrec (VBC)
- Aeeris (AER) and
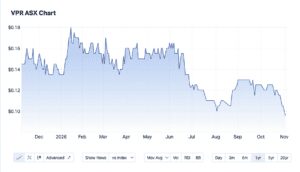
- Volt Group (VPR)
exploring what can turn an overlooked company into a rewarding investment. The common thread is growing businesses, sensible valuations and the patience to let the investment case develop.
How DMX Asset Management finds microcap opportunities on the ASX
Steven McCarthy explains that their fund focuses on emerging companies with market capitalisations below $100 million, with a median market capitalisation across the portfolio of around $50 million (at November 2026).
These companies often attract little news, research coverage or investor attention. That creates opportunities for equity investors prepared to examine the fundamentals and look beyond the next reporting period.
DMX is targeting companies with share price growth poptential, but remains disciplined about the price it pays. The aim is to buy businesses on modest earnings multiples that can grow substantially from a small base.
Patience matters because progress rarely follows a straight line. Some investments have been held for seven to ten years. Liquidity is an important consideration before you invest at this end of the market in Australia.
Diversification is another part of the approach. McCarthy’s portfolio holds around 50 stocks, with smaller initial positions given room to grow as the businesses deliver and their share prices respond.
Mergers & Acquisition activity
Takeover activity remains a feature of the microcap market, with Steven McCarthy noting that potential buyers are often looking at the same undervalued businesses as DMX Asset Management. Energy One’s rejection of an approach he considered too low highlights why a premium to the share price does not always reflect a company’s expansion potential. Kip McGrath however, shows a different example: despite opening the door to competing bidders, no rival offer emerged, leaving shareholders with only a modest improvement on the original bid.
It’s great being part of the market and finding these undiscovered companies and supporting these companies through their growth journey over the long term. Everyone benefits from these companies that are doing good things and that are able to execute on and provide services and products for society that otherwise wouldn’t exist.
6 Micro-Cap companies:
Count (CUP): Scale starts to deliver
Count had a big jump in share price, with McCarthy highlighting the benefits of scale across its accounting, financial advice and supporting services businesses.
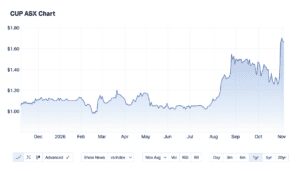
After years of acquisitions, the investment case increasingly rests on turning that larger platform into stronger earnings and cash generation. McCarthy points to the latest trading update as evidence of improving margins, supported by organic growth and acquisitions.
The attraction is operating leverage: as revenue grows, a business with an established cost base can potentially increase profits at a faster rate.
Richard and Steven also discuss how financial complexity can support demand for professional advice. For Count, the question is how effectively it can translate that demand and its growing scale into sustainable shareholder returns.
Clover (CLV): Looking beyond infant formula
Clover has always been an interesting company and has attracted interest for its technology which was developed out of the CSIRO, which allows nutritional oils to be encapsulated into powders for use in food and beverage products.
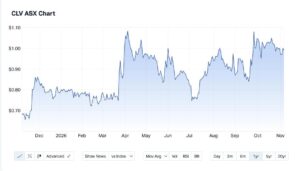
Historically, its reliance on infant formula left the business exposed to conditions in a concentrated end market. McCarthy sees a broader opportunity emerging as Clover expands its product range and applications.
There is now demand from nutrition products for older consumers, especially in China, pet food and meal replacements. These markets provide potential avenues for advancement beyond Clover’s traditional customer base.
McCarthy also highlights valuation and balance sheet strength. His investment case combines established technology with a wider growth opportunity, at a price he considers attractive at the time of the discussion.
For investors, the key is whether that diversification can translate into consistent sales and earnings increases.
LaserBond (LBL): Turning technology into commercial growth
LaserBond is another Australian business where Richard and Steven see considerable potential in the underlying technology.
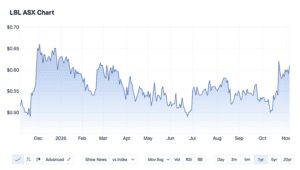
Is it Laserbond’s time in the sun?
The interview looks at the stage of commercial development: improving systems, broadening the customer base and building a larger business around the technology.
McCarthy highlights the change in management with a new CEO, and progress with major customer agreements as reasons for encouragement. The opportunity is to combine technical expertise with stronger commercial execution.
It is a familiar microcap challenge. A good product creates an opportunity, but investors need to see it reflected in revenue, profits and cash flow.
Energy One (EOL): When a takeover offer undervalues the opportunity
Energy One features in a discussion about takeover activity and the risk of selling a growing business too early.
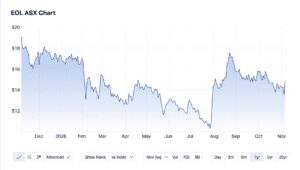
McCarthy supports the board’s rejection of the approach discussed in the interview, arguing that the business still had more of its expansion journey ahead.
The broader point is relevant across the microcap market. An offer can recognise value that the share market has overlooked, but a premium to the prevailing share price does not necessarily capture a company’s longer term potential.
Kip McGrath (KME): The limits of holding out for more
The discussion of education provider Kip McGrath gives a different perspective on takeovers.
McCarthy describes DMX’s reluctance to accept the initial offer and its support for a process that allowed other potential bidders to examine the business. However, that process did not produce the competing bid DMX had hoped for.
The experience highlights the practical balance between an investor’s assessment of value and the price a buyer is willing to pay. A shareholder can see greater potential without having the power to secure a better outcome.
Verbrec Ltd (VBC): Engineering, infrastructure and automation
The interview also touches on Verbrec, with McCarthy expressing satisfaction with its progress.
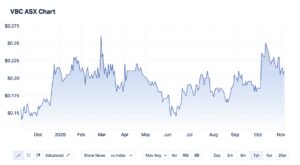
The discussion covers engineering services, water infrastructure, energy security, gas pipelines and industrial automation. McCarthy highlights the combination of a modest valuation, balance sheet strength and the opportunities arising from its expanded business.
For DMX, it fits the search for smaller companies where business progress may be running ahead of market recognition.
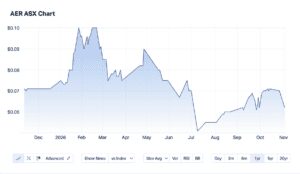
Aeeris Ltd (AER) and Volt Group Ltd (VPR): Patience with smaller companies
Aeeris and Volt Group also feature in the closing discussion of smaller company opportunities. The conversation returns to the time required for business changes to translate into results, a recurring theme in DMX’s investment approach.
Steven McCarthy Australian fund manager on the value of patience
Across the interview, Steven McCarthy returns to the satisfaction of finding undiscovered companies and supporting them through their growth.
That requires accepting uncertainty. Some investments disappoint, management changes take time and an attractive valuation does not guarantee a quick share price recovery.
For DMX Asset Management, the opportunity lies in identifying businesses that are quietly making progress, then giving that progress time to become visible.
Watch Richard Hemming’s full interview with Steven McCarthy of DMX Asset Management for more on Count, Clover, LaserBond, Energy One, Kip McGrath, Verbrec, Aeeris and Volt Group.
For full access for 7-days, to Under the Radar, click here