ASX Stock Pulse

Pureprofile (ASX: PPL): Can Global Expansion Drive Growth?

ASP_pureprofile_august 2026

Pureprofile (PPL:ASX): Can global expansion beyond Australia drive new growth for the market research technology business?

The group needs to deliver sales closer to its global peers at A$150m to A$1bn in order to be a force. This company is a recent entrant in a growing sector and there is high risk, but also very big potential. if you see free cash flow ramping up, but that’s a big if.

We see a logical step for PPL is to make an acquisition offshore to assist in growth, and if the company continues to execute on the sales front, the share price should appreciate.

We anticipate a big valuation re-rating if the pureprofile team can deliver on sales targets, on top of which you will see earnings related price improvements. 
Richard Hemming
Security data at a glance

Sector Telco | Comms
Industry Media | Advertising
Activity Global data and insights
ASX Code PPL
Share Price $0.031 (at 7 September2026)
Dividend $0.2850 per share
Net Cash $4.3m
Market Cap $34M

The investment case for Pureprofile shares?

  • We are optimistic on the future because the timing is right for international expansion.
  • Relatively strong balance sheet with net cash.
  • The company’s growth focus is on a region that is achievable, namely the UK. 
  • Aggressively growing its commercial team and has established operations in Spain and Germany.

Bull Points

Organic growth record

Market leadership in Australia

Growing offshore

Bear Points

Innovations are commoditised quickly

Highly competitive industry

Small presence in major world sector

What’s New? Market Update

We have done well to buy in at low prices because we’re benefiting from the recent spikes show a company that is growing, but remains sub-scale.

  • For FY26 to 30 June, revenue was up 14% at $65m for operating earnings (EBITDA) of $6.7m, up 24%, which was impacted by foreign currency.
  • The adjusted net profit after tax rose 51% to $3.7m, highlighting the low base this company is climbing from.
  • EBITDA/sales margin was 10%, within expectations but needs to improve.
  • A positive is that cash is climbing, now at $6.8m.

Who is Pureprofile?

Pureprofile Ltd company profile: PPL as a global research & analytics platform with online research solutions to agencies.

Essentially the company generates revenue from the market research it does on consumers from a panel that accesses its proprietary technology platform. These insights into real human behaviour direct decision-making allowing clients to deliver more value to an advertising campaign by targeting specific audiences, while consumers are rewarded for their information and responses. The company builds and conducts its own surveys, as well as through partners, such as Flybuys in Australia (Coles).

Its first-party data with cutting-edge technology and data collection provides online research to agencies, marketers, researches and brands & businesses with direct access to millions of consumers. 

How does Pureprofile make money?

The business was founded in 2000 and has been a business for over 25 years and over 850 global brands use their platform. It  has built up a data base of 50 million panellists through online surveys.  The company builds and conducts its own surveys, as well as through partners, such as Flybuys in (Coles). They provide software-as-a-service (SAAS)and research technology (ResTech). The three key revenue streams are from these products:

1. Insights – DIY research where clients build their own surveys

2. Raw intelligence – larger levels of data

3. Managed service – where Pure Profile builds and runs surveys

The researcher has built a technology platform, from which it automates some of its services.

What gives Pureprofile an edge?

Consumer insights allow the company’s customer base to gain valuable insights into customer and competitor behaviour. 

Its competitive edge is its Australian market share through partnerships with Flybuys and we believe this can be translated in bigger regions, first the UK and then the US.


Expansion offshore is occurring, but it is necessary for the scale or sales level to reach a point that ensures that profitability is consistent and then growing. 

The bedrock of the business is ANZ, where the company’s long history of surveys is complemented by the cornerstone partnerships with Coles owned Flybys and the ASX listed fintech Raiz Invest $RZI. This enables the group to obtain the data customers want – demographics, market share, consumer preferences, competitor activity.

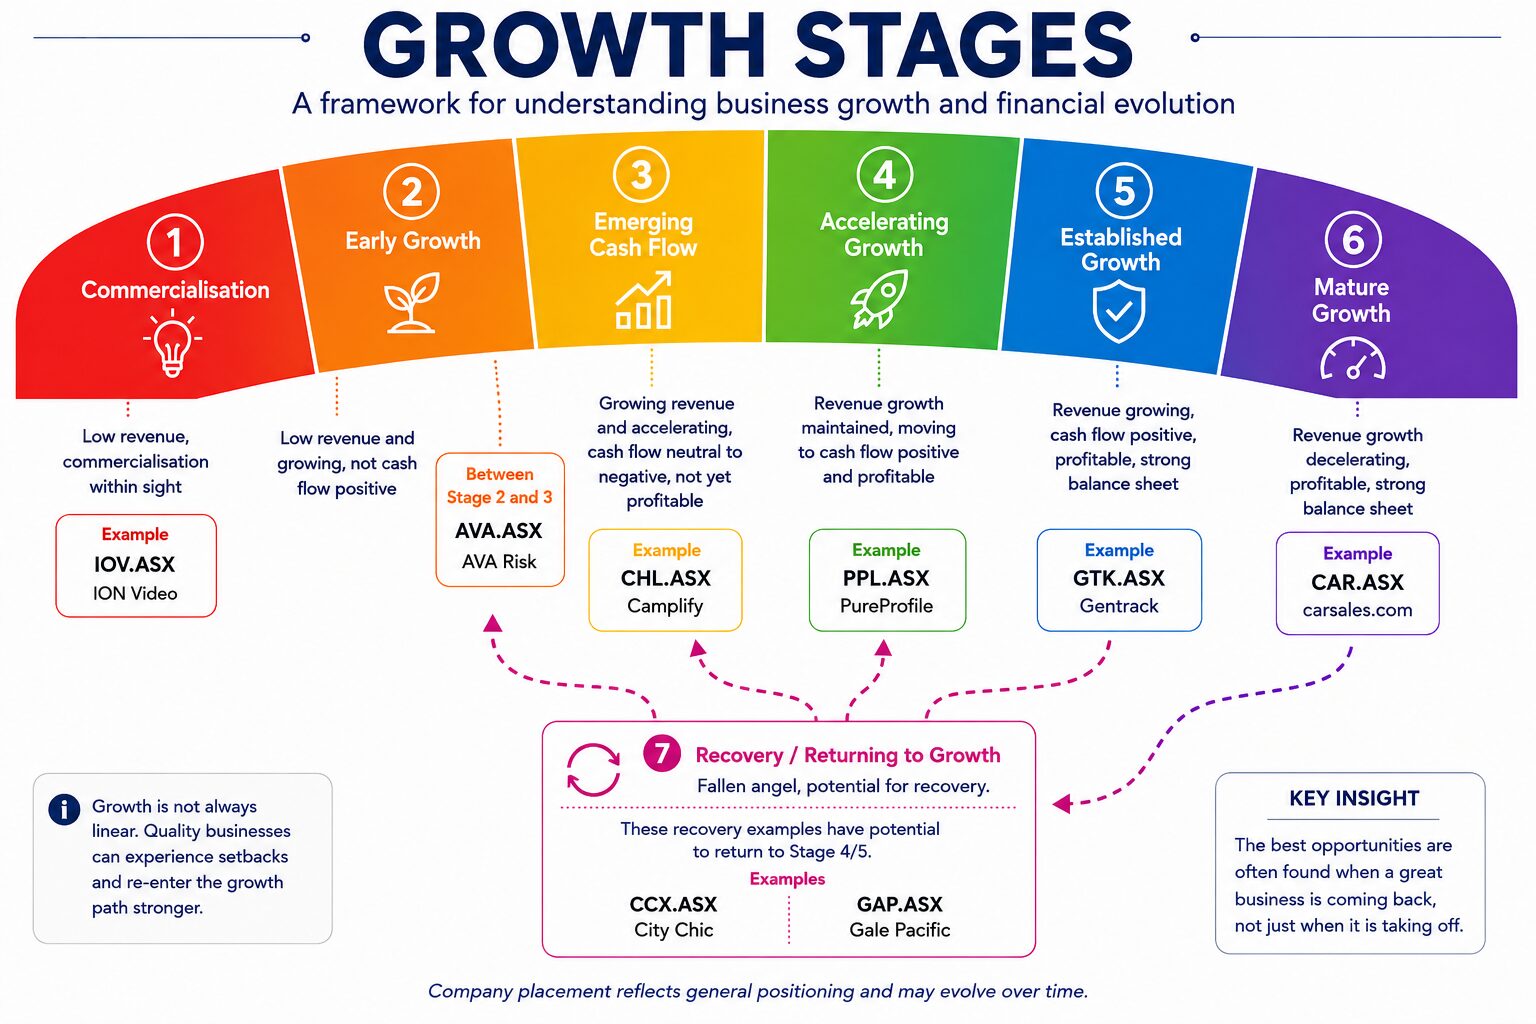
Small Cap company growth stages ASX

Detailed growth analysis for investors

As a very small company, there are high risks to growth but it’s coming off a low base.

  • Net cash, but current assets exceed current liabilities by less than $1m.
  • The business has low profit margins.
  • Investment in software is a necessary operating cost.
  • The cash generation gives much cause for optimism, the group increasing holdings by $1.1m over FY26.

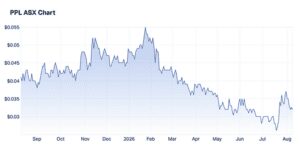
PPL Share Price Performance

Period Starting price Finish price
This Year (2026) $0.050
Last Year (2025) $0.030 to $0.049

FAQs

Questions Answered

No. Pureprofile does not currently pay a dividend. The company has historically reinvested cash flow into its ResTech platform and international expansion rather than returning capital to shareholders.

As at 5 September 2026 Pureprofile had a market capitalisation of approximately $32million against a record revenue of $2.3m (+13.7%).

Pureprofile competes with other online market research panel providers and consumer insights platforms, including global players offering survey panels, first-party data collection and research technology to agencies and brands.

Pureprofile reported EBITDA of $6.5m an increase of 24.5% for the year ending 30 June 2026.

Related Articles

NYE background

Richard Hemming

Founder, BA (Econ, maths statistics), FSIA

Richard is an experienced equities analyst, stockbroker, and financial editor, having worked for over 30 years in finance.

Recent Posts