ASX Stock Pulse

AVA Risk Group (ASX:AVA) Growing sales in a mining boom is key

AVARisk_growth_August

We need to see evidence soon that AVA Risk’s big opportunities translate into meaningful sales. These include:

  • Its agreement with Telstra.
  • Opportunities with other telecommunications companies.
  • Growth in what the company calls “adjacencies”.
  • Further contract wins in mining, defence and border security.

The core business of providing security systems for mining & national borders appears solid:

  • Sales & margins are being maintained
  • Demand from mining, government and critical-infrastructure customers remains strong
  • AVA has established products and major customers.
  • However, revenue remains below the level needed to deliver sustainable profit growth.

There is no doubt there is a great deal of operating leverage, but we need to see real evidence, not simply green shoots.

“We are keeping a close eye on this stock. Management has ambition  and we are impressed with the new CEO.”
Richard Hemming
Security Data at a Glance

Sector Information Technology
Industry Technology hardware & equipment
Activity Security technology and hardware
ASX Code AVA
Share Price $0.039 (at 7 September 2026)
Market Cap $13M
Dividend No dividend FY 30 June 2026
Net cash $0.8m

The Investment Case for AVA Risk Shares?

The industrial stock is in the growth phase with investment patience needed while the company turns its sales pipeline into contracts and cash flow.

The investment case centres on several key points:

  • Management is targeting annual sales of $70-100m in the next few years.
  • This is more than double current revenue
  • Demand should not be a factor, with commodities at record levels.
  • Announcements thus far indicate it will be a stretch and cash levels are low. The stock is good value if sales can be achieved, but uncertainty is high.

Bull Points

Strong customer base of governments & big corporates

Technology for the times

New CEO highly regarded

Bear Points

Sales going the wrong way

Loss making

Subscale for the opportunity

What’s New? Market update

FY26 Revenue of just under $29m, better than we expected but still below guidance of $34-37m and led to a loss of $3.2m.

The Middle East problems are a factor, but the balance sheet remains resilient with cash at $5.3m, receivables just under $10m and inventories of $6.4m.

Net current assets is comfortable at over $10m, hence the company shouldn’t have a problem with $4.5m in debt due this year. However the big issue is sales, which are slipping, leading to structural losses for the Australian security specialist.

Last month new chief executive officer Bryant Henson put his feet under the desk. He has deep experience in defence, aerospace, government, communications and critical infrastructure. He was a senior executive with Lockheed Martin and most recently Otis Worldwide, where we was in charge of business development globally.

Who is AVA Risk?

Ava Risk Group (AVA) is a global leader in providing technologies and services to protect critical and high-value assets and infrastructure. It operates three business segments– Future Fibre Technology (FFT), BQT Solutions (BQT) and GJD Manufacturing (GJD).

  1. FFT manufactures and markets smart fibre optic sensing systems for security and condition monitoring for a range of applications including perimeters, pipelines, conveyors, power cables and data networks.
  2. BQT is a specialist in the development, manufacture and supply of high-security biometric readers, security access control and electronic locking products.
  3. GJD is a specialist in the development and manufacture of perimeter detectors, illuminators, and ANPR cameras.

How does AVA Risk make money?

AVA has three divisions, but the key is “Detect”, which generates over half of sales from fibre optic sensing technologies, one being Aura Ai-X used by mining companies. The company is making more noise about country boundary sensing business, which is not surprising given the stage of geopolitical uncertainty. 

“Access” sells a locking technology and has a deal with the global giant dormakaba, signed late CY21, unlocking US and Europe. 

“Illuminate” develops automatic number plate recognition cameras and perimeter detectors. This business has performed below expectations, resulting in a $1.5m write-down of goodwill. 

What gives AVA Risk an edge?

There is certainly demand for the group’s security services and products from mining, transport and countries, such as Poland, which have common boundaries. The diverse range of income is impressive. A problem has been long sales-lead times.

Growth Stages

A framework for understanding business growth and financial evolution
Growth is not always linear. Quality businesses can experience setback and re-enter the growth path stronger.
Key Insight

The best opportunities are often found when a great business is coming back, not just when it is taking off.

Company placement reflects general positioning and may evolve over time.

Detailed growth analysis for investors

FY27 is very important. AVA has $6.8m of sales order backlog, including $2.6m contracted annual recurring revenue and a global commercial team that should be buoyed by new leadership.

Stage 2/3 positioning is based on real products and established customers, but the challenge is still converting large opportunities like Telstra into repeatable, material revenue growth.

This company has been around for a while and has previously produced dividends and growth. The group did will to sell its Services Division, AVA Global base in October 2021 for US$46.4m (A$63.1m) but has been has struggled since then. 

There has been promise in the recent years, but a significant set back has been that the Telstra contract has not lived up to the promise, simply being a preferred supplier agreement under which individual orders could be placed. AVA secured a $0.3m Aura Ai-X system to project a subsea cable, which was successful.

“FY2027 is focused on execution. The Company expects performance to be significantly stronger than FY2026, with management concentrating on converting existing opportunities and demonstrating the operating leverage inherent in the business model.”

Bryant Henson, Chief Executive Officer

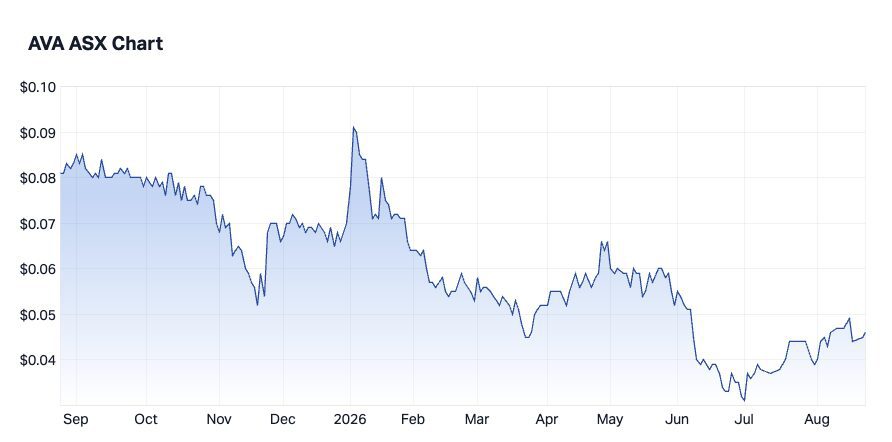
AVA Share Price Performance

Period Starting price Finish price
This Year (2026) $0.071
Last Year (2025) $0.013  to $0.07

This is general information only and does not take into account your objectives, financial situation or needs. It is not a recommendation to buy, sell or hold any security.

FAQs

Questions Answered

No dividend FY 30 June 2026

As at 4 September 2026, AVA had a market capitalisation of $13M.

AVA competes with other providers of perimeter intrusion detection, fibre-optic sensing and physical security technology serving critical infrastructure, government and industrial customers, both in Australia and internationally.

For the financial year ended 30 June 2026, Ava Risk Group Limited reported a positive group underlying EBITDA of $0.1 million.

AVA’s fibre-optic sensing technology is used to protect pipelines, perimeters and remote infrastructure, which makes mining and resources a key end market. Demand from mining-sector capital spending is a driver of AVA’s sales pipeline, though it also sells into government, utilities and other critical-infrastructure customers.

If you are new to investing, our guide on how to buy shares on the ASX covers the basics.

Related Articles

NYE background

Richard Hemming

Founder, BA (Econ, maths statistics), FSIA

Richard is an experienced equities analyst, stockbroker, and financial editor, having worked for over 30 years in finance.

Recent Posts